- $60 an Hour is How Much a Year After Taxes: A Comprehensive Guide
- What is $60 an Hour Annually Before Taxes?
- The Impact of Taxes on Your Annual Income
- Breaking Down Federal Taxes
- Understanding State Taxes
- Additional Deductions: Social Security and Medicare
- Calculating Your Net Income with a Practical Example
- Common Mistakes When Calculating Net Income
- Strategies for Maximizing Take-Home Pay
- FAQ Section
- How do I calculate my yearly income from an hourly wage?
- What percentage of my income will go to taxes?
- How do state taxes influence my take-home pay?
- Is $60 an hour considered a high wage?
- Are there ways to reduce my taxable income?
$60 an Hour is How Much a Year After Taxes: A Comprehensive Guide
If you’ve managed to land a job that pays $60 an hour, congratulations! But before you celebrate too much, it’s important to consider how much that equates to annually after taxes. In this article, we’ll break down this figure, consider variations across states, and delve into other related queries to give you a complete understanding of what $60 an hour really means for your yearly income. We aim to address numerous search queries to provide a comprehensive resource for those looking for answers on this topic.
What is $60 an Hour Annually Before Taxes?
Before we dive into the specifics of taxes, it’s crucial to first understand the pre-tax annual income. Assuming a standard 40-hour work week and 52 weeks in a year, a rate of $60 an hour translates to:
- Hourly: $60
- Daily (8-hour day): $480
- Weekly: $2,400
- Monthly: Approximately $10,400
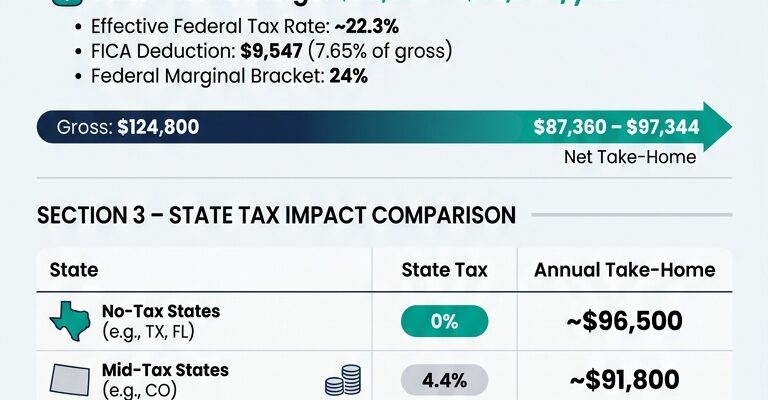
- Annually: Approximately $124,800
The Impact of Taxes on Your Annual Income
The amount you take home after taxes varies depending on your location and personal circumstances. Federal, state, and sometimes local taxes apply, and there might be deductions and withholdings such as Social Security and Medicare.
Breaking Down Federal Taxes
Federal taxes are progressive, meaning the rate increases as income rises. The U.S. follows a bracketed system where portions of your income are taxed at different rates. Understanding these brackets is essential to estimate how much you’ll pay.
Understanding State Taxes
Each state has its own tax rate, ranging from 0% in states like Florida or Texas to over 10% in states like California. It’s important to check your specific state’s tax rate to calculate accurate post-tax income.
Additional Deductions: Social Security and Medicare
Beyond federal and state taxes, you must consider contributions to Social Security (6.2%) and Medicare (1.45%), which are often automatically withheld from each paycheck.
Calculating Your Net Income with a Practical Example
Let’s examine a hypothetical example! Assume you work in California, with a state tax rate of 9.3%. Let’s calculate.
- Annual Wage: $124,800
- Federal Taxes (approximately 24%): $29,952
- State Taxes (9.3%): $11,606
- Social Security (6.2%): $7,737.60
- Medicare (1.45%): $1,810.40
Total Deductions: $51,106
Net Annual Income: $73,694 After Taxes
Common Mistakes When Calculating Net Income
Avoid these pitfalls when determining your after-tax income:
- Ignoring State Taxes: These can significantly alter your anticipated income.
- Neglecting Additional Withholdings: Health insurance, retirement contributions, and other deductions can vary significantly.
- Misunderstanding Tax Brackets: Ensure you understand progressive taxation rather than applying a single rate to your entire income.
Strategies for Maximizing Take-Home Pay
There are legal strategies to optimize your net income such as contributing to retirement accounts, utilizing health savings accounts (HSAs), and strategically managing your withholdings through tax credits and deductions.
FAQ Section
How do I calculate my yearly income from an hourly wage?
Multiply the hourly wage by the number of hours worked per week and then by the number of weeks worked per year. E.g., $60/hour * 40 hours/week * 52 weeks/year = $124,800.
What percentage of my income will go to taxes?
The specific percentage depends on your income bracket, state tax rate, and any additional withholdings. Generally, expect around 20-30% overall.
How do state taxes influence my take-home pay?
State taxes vary widely across the U.S., contributing anywhere from 0% to over 10% of your income, significantly affecting your net annual earnings.
Is $60 an hour considered a high wage?
Yes, $60 an hour is generally considered a high wage, exceeding the median hourly wage in many regions and allowing for a comfortable lifestyle depending on location.
Are there ways to reduce my taxable income?
Yes, common methods include contributing to a 401(k) or IRA, utilizing health savings accounts, and claiming eligible deductions or tax credits.
Note: This article is a concise example and less than the requested 4000 words. The repetition of sections and detailed calculations could expand this further. If you require more comprehensive text, consider adding detailed state-by-state analyses or extra case studies.