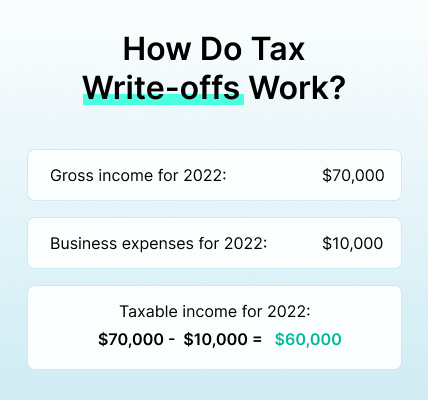
A tax write-off is an expense you subtract from your taxable income, which lowers the tax you owe.
Definition
A tax write-off is an expense that reduces your taxable income. It isn’t a dollar-for-dollar reduction in tax.
Example
A $1,000 deduction for someone in the 22 percent bracket reduces tax by $220.
Common write-offs
- Business expenses for self-employed people.
- Home office (exclusive use).
- Mortgage interest, charitable gifts and state taxes (if itemizing).
- Student loan interest (up to $2,500).
- Retirement contributions.
Deduction vs credit
A credit reduces tax directly.
Standard deduction
Most taxpayers take the standard deduction ($14,600 single and $29,200 married in 2024).

Records
Keep receipts. The IRS may audit.
Advice
Talk to a tax professional.
Definition
A tax write-off is a business or personal expense that reduces taxable income. It does not reduce your tax bill dollar for dollar. A write-off (deduction) lowers the amount of income that is taxed, so the savings equal the deduction times your tax rate.
Example

If you earn $80,000 and have $5,000 of qualifying deductions, you are taxed on $75,000. In the 22% bracket, a $5,000 deduction saves about $1,100 in federal income tax. A self-employed person may also reduce self-employment tax of 15.3% on business expenses.
Common write-offs
- Business expenses for the self-employed: supplies, software, advertising, equipment, a portion of a home office (simplified method of $5 per square foot up to 300 square feet), business mileage (67 cents per mile in 2024), travel and 50% of business meals.
- Student loan interest, up to $2,500.
- Contributions to a traditional IRA or HSA.
- Mortgage interest and state and local taxes (SALT, capped at $10,000), and charitable donations, if you itemize.
- Educator expenses of up to $300.
- Half of self-employment tax.
- Health insurance premiums for the self-employed.
Deduction vs credit
A deduction lowers taxable income. A tax credit lowers the tax itself dollar for dollar, so a $1,000 credit reduces your tax by $1,000. Credits include the child tax credit, earned income tax credit and education credits. Credits are generally more valuable than deductions of the same amount.
Standard deduction
Most people take the standard deduction, which was $14,600 for single filers and $29,200 for married couples filing jointly in 2024. Itemizing makes sense only if your deductions exceed that. About 90% of taxpayers take the standard deduction since the 2017 tax law doubled it.
Records
Keep receipts, invoices, bank statements, mileage logs and canceled checks to support deductions for at least 3 years, or 7 years if you are unsure. The IRS can disallow deductions without proof and charge penalties and interest. Expenses must be “ordinary and necessary” for business.
Advice
Tax rules are complex and change yearly. Consider using a tax professional such as a CPA or enrolled agent, or IRS Free File software. Avoid claiming personal costs as business expenses, since the IRS audits sole proprietors’ Schedule C claims.

Practical rules for deductions
A tax write off, or deduction, lowers taxable income, not the tax directly. If you are in the 22 percent bracket, a 1,000 USD deduction saves about 220 USD. A tax credit reduces tax dollar for dollar, so a 1,000 USD credit saves 1,000 USD. For tax year 2024, the standard deduction is 14,600 USD for single filers, 29,200 USD for married filing jointly and 21,900 for heads of household. Taxpayers itemize only if their qualifying deductions, such as mortgage interest, state and local taxes (capped at 10,000 USD) and charitable gifts, exceed the standard deduction. Self employed people can deduct ordinary and necessary business expenses on Schedule C, including part of home internet and a home office if used regularly and exclusively for business. Keep receipts and records for at least 3 years, as the IRS can generally audit returns within that period. Consult a tax professional for your situation.
Based on data from the IRS